When diesel gets tight, attention turns quickly to any fuel that can move freight, harvest crops, power equipment, and keep supply chains running without changing engines. That is why more countries are reconsidering biodiesel, particularly renewable diesel, as oil-supply disruptions drive up fuel costs and expose the risks of relying on imported petroleum. While renewable diesel cannot fully replace the petroleum diesel market, it is one of the few options that can add usable gallons to the existing fuel system right away.
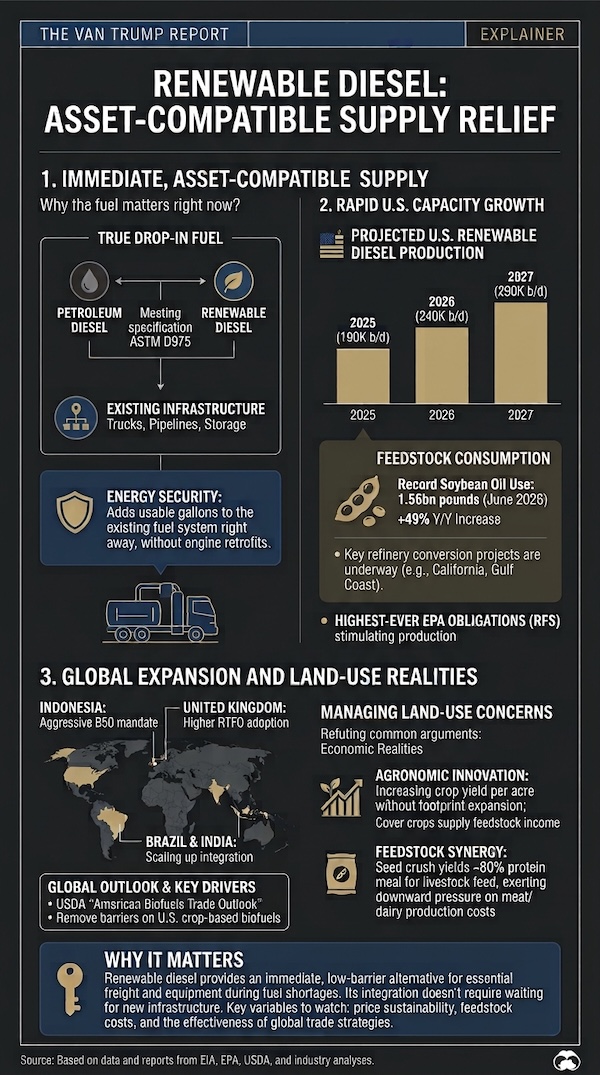
Renewable diesel stands out as a true drop-in fuel. Unlike conventional biodiesel, which is usually blended into petroleum diesel at limited percentages, renewable diesel is processed into a fuel that meets the same ASTM D975 specification as petroleum diesel. That compatibility means that traditional diesel fuel users do not have to wait for new trucks, charging depots, or engine retrofits. If supply is available, they can use the fuel now. It can also move through existing storage, pipelines, and fueling systems without special equipment changes.
The United States has built a sizable renewable diesel industry, though not one large enough to solve the diesel market on its own. The EIA currently predicts renewable diesel production will average 240,000 barrels per day this year, expanding to 290,000 barrels per day in 2027. Renewable diesel production averaged 190,000 barrels per day in 2025. For comparison… In 2025, total U.S. distillate fuel oil (diesel) consumption averaged approximately 3.8 million to 4.0 million barrels per day across all sectors (with transportation accounting for about 2.94 million barrels per day of petroleum-based diesel). Today, total U.S. distillate petroleum diesel consumption sits right around 3,900,000 barrels per day. Industry insiders believe “renewable diesel” supplied roughly 4.8% to 5.0% of the overall U.S. diesel pool in 2025.
As domestic refining capacity grows toward 300,000–330,000 barrels per day (5.5-6.0 billion gallons per year), renewable diesel is expanding its share, but it remains a supplemental drop-in fuel to a market still overwhelmingly dominated by standard petroleum diesel. Large-scale refinery reconfigurations—such as the Phillips 66 Rodeo Renewed project in California and Marathon’s Martinez facility—alongside major Gulf Coast processing facilities are driving this rapid increase.
Here in the US, EPA’s finalized Renewable Fuel Standard for 2026 and 2027 sets its highest-ever renewable fuel obligations, including total biomass-based diesel requirements of 9.07 billion RINs in 2026 and 9.20 billion RINs in 2027, after small refinery exemptions. Those provisions, announced in March, took effect in June, and appear to be further stimulating production.
EIA data showed that domestic biofuel producers used a record 1.56 billion pounds (707,604 tonnes) of soybean oil in June, up by +9% from the previous high of 1.43 billion pounds (648,637 tonnes) the previous month. The figure was also 49% up year-on-year, compared with 1.043 billion pounds (473,096 tonnes) used in June 2025. The US biodiesel sector consumed 790 million pounds (358,337 tonnes) of soybean oil in June, up by 5.8% from 747 million pounds (338,833 tonnes) the previous month. Domestic renewable diesel producers, by comparison, used 766 million pounds (347,451 tonnes) of soybean oil in June, up by +11.5% from 687 million pounds (311,617 tonnes) the previous month.
Several other countries and regions are actively increasing or proposing higher renewable diesel and biodiesel blending mandates to improve energy security, as well as lower greenhouse gas emissions:
- Indonesia: Continues aggressive expansion of its biodiesel programs, moving forward with plans targeting a higher B50 (50% blend) biodiesel mandate.
- Malaysia: Is working to expand its nationwide biodiesel requirements up to a B20 mandate.
- United Kingdom: Uses the UK Renewable Transport Fuel Obligation to push commercial fleets and suppliers toward higher adoption of drop-in renewable diesel and hydrotreated vegetable oil (HVO).
- India & Brazil: Both are scaling up overall biofuel integration significantly as part of broader national energy security and net-zero commitments
- European Union: Member states are implementing the European Union Renewable Energy Directive (RED III), shifting toward greenhouse gas (GHG) reduction systems that heavily reward advanced renewable diesel like HVO.
The US is trying to situate itself as a key supplier as these global plans take shape. On September 15, U.S. Agriculture Secretary Brook Rollins announced the launch of USDA’s new “American Biofuels Trade Outlook,” a four-part strategy aimed at boosting export opportunities for U.S. biofuel producers. The first pillar of the plan focuses on increasing on-road ethanol blending. Rollins says the USDA will identify markets like those in Latin America and Southeast Asia that are “prime for E10 adoption.” The second pillar, which is key for bio-based diesels, aims to reduce and remove restrictions that other nations have placed on U.S. crop-based biofuels. Rollins notes that several countries currently restrict crop-based biofuels, including the European Union.
Crop-based biofuels have come under fire over land-use concerns. Some groups warn that aggressive global biofuel expansion could intensify competition for cropland and vegetable oils. Most study conclusions on land competition rely on static assumptions that ignore key developments in modern renewable fuel production, particularly in the renewable diesel sector
Modern agronomy continues to increase crop yield per acre without expanding the physical footprint. Furthermore, cover crops like Camelina or Carinata can be grown on existing cropland during winter off-seasons, providing secondary feedstock income for farmers without competing with summer food crops.
What’s more, when soybeans or canola are crushed for oil, roughly 80% of the seed mass remains as high-protein meal used directly in livestock feed. Expanding biofuel capacity increases the global supply of protein meal, which can exert downward pressure on meat and dairy production costs rather than causing food shortages.
The bigger issue is durability. Renewable diesel looks especially attractive when petroleum diesel is scarce and expensive, but the industry will be tested if those dislocations ease. If diesel prices fall back and feedstock costs stay high, weaker projects could struggle, especially those built around the expectation of permanent crisis-level margins. Still, that does not mean the renewable diesel push disappears once the emergency passes. The fuel has lasting strengths: it works in today’s diesel engines, fits the existing distribution system, and offers a domestic supply option for sectors that are still difficult to electrify. (Sources: EPA, EIA, Chatham House, Biodiesel Magazine, Terrain Ag)